FTA Decision 13 of 2026: A Valid Tax Invoice Is No Longer Enough
From 1 October 2026, holding a valid tax invoice will not by itself secure input VAT recovery in the UAE. You will also need documented proof that you checked who you were dealing with before you claimed the deduction.
Two instruments take effect on that date. FTA Decision No. 13 of 2026 makes supplier and supply verification mandatory. Cabinet Decision No. 149 of 2026 rewrites parts of the VAT Executive Regulation, restricting what is recoverable at all. Together with Cabinet Decision No. 100 of 2024, they mark a shift in how UAE VAT compliance is assessed.
The change in one sentence
UAE VAT has moved from “do you hold a valid tax invoice?” to “can you prove you checked who you were dealing with, and why?” — and the burden of proof now sits with the taxpayer.
Awareness is low, and that is the risk
Decision 13 was issued on 22 July 2026 but only appeared on the FTA website on 20 August 2026. That left a short window before the 1 October effective date, and many businesses have not yet built the process it requires.
Why FTA Decision 13 exists ?
It answers a question created by an earlier amendment.
Federal Decree-Law No. 16 of 2025 inserted Article 54(bis) into the VAT Law with effect from 1 January 2026. That article gives the Federal Tax Authority power to deny input tax recovery where a supply forms part of a chain connected to tax evasion and the recipient knew, or should reasonably have known, of that connection.
Which left an obvious practical gap. What does “should have known” require of a business claiming input tax in good faith?
Decision 13 prescribes the answer: the specific measures, procedures and conditions a taxable person must follow to demonstrate reasonable care before deducting input tax. Follow them and you have evidence of diligence. Fail to, and you risk being treated as having known.
Who it applies to ?
Every taxable person under the VAT Law — any business registered, or required to be registered, for UAE VAT. There is no exemption by size or sector. The only relief comes through the monetary thresholds set out below, which govern how much work you do rather than whether you do any.
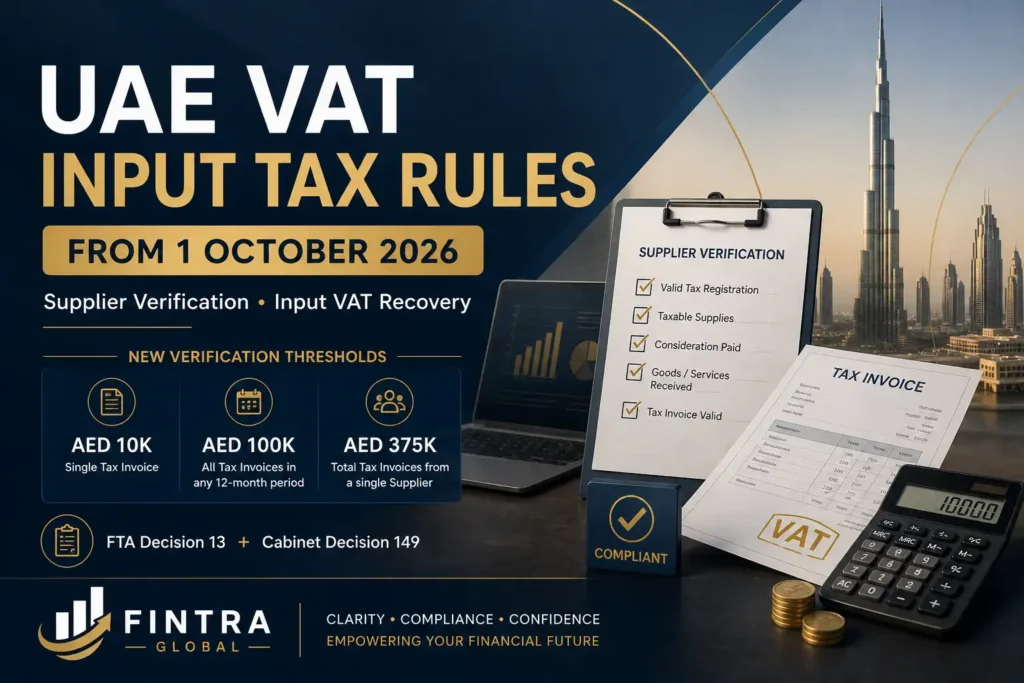
The three thresholds..
These determine the depth of verification required, and the interaction between the first two is where most businesses will go wrong.
| Threshold | What it triggers |
|---|---|
| AED 10,000 | Per supply, excluding VAT. Below this value the verification measures may be skipped entirely. |
| AED 100,000 | Per supplier over 12 months, past or expected. Once crossed, the AED 10,000 exception no longer applies — full verification is required regardless of individual invoice size. |
| AED 375,000 | Per supplier over 12 months. Triggers the additional enhanced checks under Article 3(4): written bank confirmation and a reputation review of publicly available information. |
The trap. The AED 10,000 per-supply exception is not standalone. A supplier invoicing you AED 8,000 a month never issues a single invoice above AED 10,000 — but twelve months at that rate is AED 96,000, and an ongoing relationship crosses AED 100,000 early in year two. At that point full verification applies to every supply, including the small ones. And the test is “past or expected”, so you cannot wait for the breach.
Supplier verification under Article 3
Before relying on input tax from a new supplier — or an existing supplier not checked in the past twelve months — you must confirm the following.
| Check | What is required |
|---|---|
| Identity: individual supplier | A copy of a valid Emirates ID or passport, plus an in-person or virtual meeting before the supply is made. |
| Identity: company supplier | Verified incorporation details matched against official databases, or a certificate of incorporation, together with identity documents for the authorised representative dealing with your business. |
| Address and place of business | Confirmation, through electronic checks or a site visit, that the supplier has a genuine place of business consistent with the nature of its activities. |
| Risk indicators | That the supplier has not changed address or key personnel more than twice in the past twelve months, and that transaction volumes are proportionate to its size and history. Where a red flag applies, keep a documented, justified explanation on file. |
| Enhanced checks (above AED 375,000) | Written bank confirmation and a reputation check reviewing publicly available information. |
The requirement most likely to be missed
For an individual supplier, the meeting must happen before the supply is made — not at invoicing, and not afterwards. If you engage individual contractors or freelancers, this changes the order of your onboarding process, not just its paperwork.
Supply verification under Article 4
Separately, and for each taxable supply received, you must check:
- The transaction has a genuine commercial rationale.
- Payment terms are commercially justifiable. Third-party payments, or payments to accounts outside the supplier’s home country, need a documented explanation.
- Payments are made electronically where possible. Cash payments need a clear commercial reason and must stay within legal thresholds.
- Prices and profit margins are not unexplainably out of line with the market.
- The goods or services fall within the supplier’s normal licensed activity.
- The origin and ownership of goods received can be verified.
- Where a supplier acts as an intermediary, there is a clear commercial reason for their role in the chain.
Points five and seven are worth reading together. A supplier invoicing outside its licensed activity, and unexplained intermediaries in a supply chain, are recognised missing-trader and carousel fraud indicators. The FTA has imported established fraud-detection markers directly into the conditions for recovery.
Documentation and governance under Article 5
The decision does not only require the checks. It requires evidence that they were performed.
- Verify each supplier on first dealing, and again once twelve months have passed since the last check.
- Verify every taxable supply received against the Article 4 criteria.
- Retain supporting documents and records showing how each verification step was carried out, in a form the FTA can review.
- Maintain a written policy naming the people responsible for running, reviewing and supervising the verification process, with their roles clearly defined.
That last requirement, in Article 5(4), is a governance obligation rather than a tax one. Someone in the business must formally own supplier verification, with defined powers and responsibilities. It is also the easiest thing for an auditor to ask for, and the easiest to be caught without.
What non-compliance costs ?
Decision 13 sets out due diligence requirements rather than penalties. There is no fixed fine for failing to verify.
The exposure is worse than a fine. Failing to verify as required means a business risks being treated as having known or should have known about a tax evasion link under Article 54(bis) — which allows the FTA to deny input tax recovery on the related supplies.
The cost is the input tax itself, on every affected supply, potentially across multiple periods, plus late payment consequences on the resulting underpayment. For a business with significant supplier spend, that is an open-ended exposure rather than a capped penalty.
Cabinet Decision 149 of 2026: what else changes ?
Issued 1 September 2026 and generally effective 1 October 2026, this decision amends Cabinet Decision No. 52 of 2017 (the VAT Executive Regulation) across several areas.
Employee benefits and the accommodation carve-out
Amended Article 53 addresses input tax where an employer provides goods or services to employees. Recovery may be available where the benefit is either mandatory under applicable labour legislation in the UAE or in a free zone — expressly including financial and non-financial free zones such as DIFC and ADGM — or arises from a contractual obligation or documented company policy.
The restriction that matters
Accommodation provided by an employer is excluded from the first category unless its provision is mandatory under decisions or directives issued by the Ministry of Human Resources and Emiratisation. For construction, hospitality, healthcare and aviation businesses that house staff as standard, “we always provide accommodation” is not sufficient. The question is whether MOHRE mandates it.
Where recovery rests on the second limb, the documentation is the evidence. An undocumented practice will not support the claim, so employment contracts and HR policies need reviewing before October.
The Capital Asset threshold is now AED 5 million
For the Capital Asset Scheme, a Capital Asset is now a business asset costing AED 5,000,000 or more excluding VAT, on which VAT is payable, with a useful life of ten years or more for a building or part of a building, or five years or more for other assets.
Re-run your fixed asset register against this. Assets previously inside the scheme may now fall out, and assets previously outside may now fall in — which changes which assets require ongoing Capital Asset Scheme adjustment over the monitoring period. That is a systems change, not a definitional one.
A new restriction on cash payments
New Article 54(3) provides that input tax may not be recovered on a supply exceeding an amount to be specified in a Ministerial decision where the consideration is paid, or intended to be paid, in cash.
The framework exists from 1 October 2026. The monetary threshold and controls do not — they will come through a separate Ministerial decision still awaited.
Read alongside Decision 13, which already requires electronic payment where possible and a clear commercial reason for cash, the direction is unambiguous: cash is being squeezed out of recoverable VAT. Map your current cash payment practices now and begin migrating significant payments to electronic channels, rather than waiting for the number.
Composite supplies and the economic substance test
New Article 4(6) provides that a supply containing more than one component will not automatically be treated as multiple separate supplies where the nature of the supply and its economic substance show the components are interconnected and cannot be separated. In those circumstances it is a single composite supply, taking the VAT treatment of its principal component.
This cuts both ways. A bundle you currently split may now be a single supply taking the principal component’s rate, which could move revenue from exempt to taxable or the reverse. Businesses with bundled products or services should revisit their contracts and current treatment.
Tax credit notes: the exact wording
Amended Article 60 expressly requires the words “Tax Credit Note” to be clearly displayed on the document. Many ERP systems output documents headed “Credit Note”, “Credit Memo” or “Adjustment Note”.
A small change, and a genuinely easy failure. It is also exactly the sort of formal defect an FTA audit identifies immediately, across every document in a period. Check your invoicing templates.
The apportionment rewrite does not start in October
The most commonly misstated point
The revised Article 55 apportionment provisions — including new Clauses 6, 7 and 19 — do take effect on 1 October 2026. They apply from the first Tax Year commencing after 1 October 2027.
That gives businesses a further year, and it is worth using rather than banking. Two changes will alter the result your current calculation produces.
First, certain amounts are now excluded from the apportionment percentage: supplies of Capital Assets attributable to the taxable person, and the receipt of Concerned Goods and Concerned Services under Article 48. A one-off disposal of a major asset, or a large volume of reverse-charge imports, could previously distort the ratio in a single period. Excluding them produces a percentage that better reflects the ongoing business mix — but if your current method includes them, the new rules will give you a different answer.
Second, new Clause 19 gives Government Entities and Charities an entirely separate methodology. The general method is output-based, comparing values of supplies. The Government Entity and Charity method is input-based, comparing amounts of input tax. That distinction makes sense, since such bodies often have substantial activity generating no supplies at all, which would make an output-based ratio meaningless.
Where Cabinet Decision 100 of 2024 fits
Effective 15 November 2024, this was the earlier broad amendment of the Executive Regulation, interpreted by the FTA in Public Clarification VATP040 in March 2025. Several of its changes remain live points in practice:
- Medical insurance input tax became recoverable for employees, a spouse and up to three children under 18, regardless of whether there is a legal obligation to provide it. The change is not retrospective — for a premium paid in January 2024 covering the full year, only the VAT on the portion from 15 November to 31 December 2024 is recoverable.
- Export of services is tested on the total days a non-resident recipient is present in the UAE across a rolling twelve-month period. More than 30 days and the recipient is regarded as being in the UAE. A shorter presence only counts as outside the State if it is not effectively connected with the supply.
- Deemed supply — where the AED 2,000 output tax threshold over twelve months is exceeded, only the amount in excess is payable. It operates as a genuine allowance, not a cliff edge.
- Simplified tax invoices are not permitted where the Article 48 reverse charge applies.
What to do before 1 October ?
- Segment your supplier base by rolling twelve-month spend against the AED 10,000, AED 100,000 and AED 375,000 thresholds — including expected spend, not just historic.
- Collect or refresh identity and incorporation documents for every supplier above AED 100,000, and arrange bank confirmations and reputation checks for those above AED 375,000.
- Confirm each supplier’s place of business is consistent with what they invoice you for.
- Write the verification policy and name the owner. Article 5(4) requires it, and it is the first document an auditor will ask to see.
- Add the pre-supply meeting step to onboarding for individual suppliers.
- Flag and document all cash, third-party and offshore account payment arrangements, and begin moving significant cash payments to electronic channels.
- Document the accommodation position — MOHRE mandate or not — and review employee benefits against amended Article 53.
- Re-test the fixed asset register against the AED 5 million Capital Asset threshold.
- Update tax credit note templates so the required wording appears.
- Brief procurement and accounts payable. Most of this work happens in their process, not in the tax return.
Most of the effort here sits in procurement and accounts payable rather than in tax. That is the practical difficulty: the obligation is a tax one, but the process change lands on teams who do not usually read FTA decisions.
How Fintra Global can help
The work here is operational rather than advisory, and it needs to be in place before 1 October.
We segment your supplier base against the three thresholds, identify which suppliers need documents collected or refreshed, draft the written verification policy Article 5(4) requires, build the record retention structure the FTA can review, and brief your procurement and accounts payable teams on the new onboarding sequence. Alongside that we review employee benefits and the accommodation position under amended Article 53, re-test the fixed asset register against the AED 5 million Capital Asset threshold, and check your tax credit note templates.
Not sure whether your supplier files would survive an FTA review? fintraglobal.com · +971 55 467 2256
This article is general guidance current as at September 2026 and is not tax advice. It is based on Cabinet Decision No. 100 of 2024, FTA Public Clarification VATP040, Cabinet Decision No. 149 of 2026 and FTA Decision No. 13 of 2026. The published texts should be consulted on specific positions, particularly the precise wording of the verification criteria and the apportionment formulae.