Withholding Tax in the UAE: Why 0% Does Not Mean “No Withholding Tax”
If you have searched for UAE withholding tax, you are probably looking for one of two answers. Either you want to know whether you must deduct tax before paying a foreign supplier or shareholder, or you want to know why a foreign customer has deducted tax before paying you.
The first question takes seconds to answer. The second is where the real work sits, and it is the one most businesses do not realise they have.
The short answer
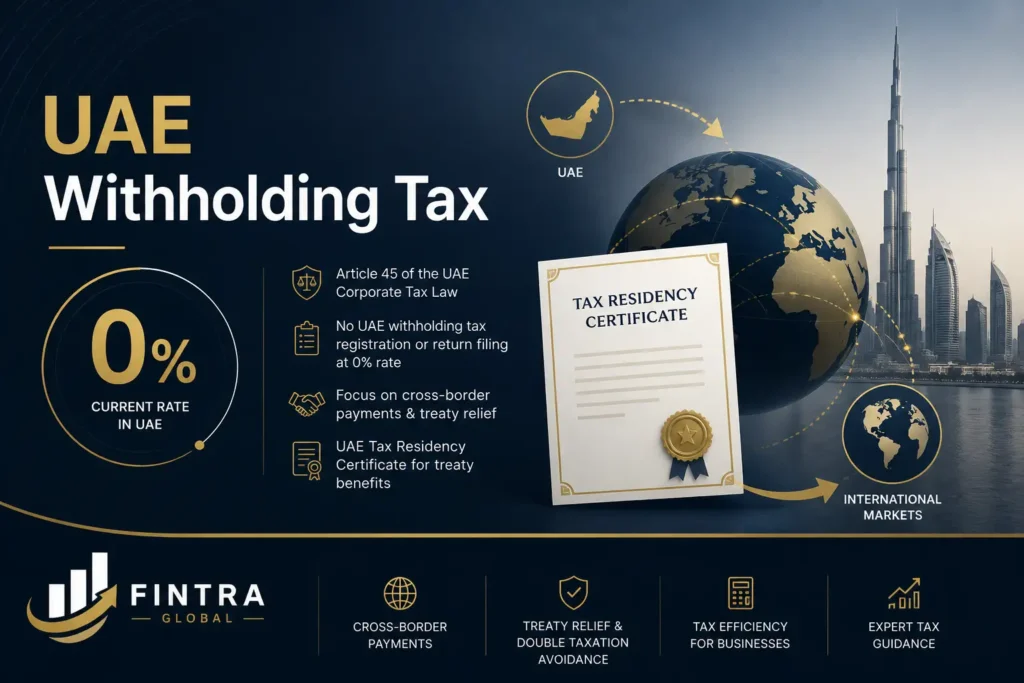
The UAE withholding tax rate is 0%. There is nothing to deduct, no withholding tax registration, and no withholding tax return to file.
That said, the UAE does have a withholding tax framework. The distinction between “no withholding tax” and “withholding tax set at zero” is not pedantry — it affects how your payments are treated abroad, and it determines how much notice you would get if the position ever changed.
What is withholding tax?
Withholding tax is tax deducted at source. Rather than the recipient paying it later, the payer holds back a percentage of the payment and remits it directly to the tax authority.
Most countries apply it to cross-border payments — dividends, interest, royalties, and service or management fees paid to non-residents — at rates commonly between 5% and 30%. It is an efficient way for a tax authority to collect from someone outside its jurisdiction, because it uses the local payer as the collection agent.
Does the UAE charge withholding tax on payments to non-residents?
No. The rate is 0% across every category of payment.
Article 45 of Federal Decree-Law No. 47 of 2022 (the Corporate Tax Law) creates the withholding tax mechanism. It applies to categories of UAE-sourced income derived by a non-resident person, where that income is not attributable to a Permanent Establishment of the non-resident in the UAE.
Critically, the law itself does not set the rate. Article 45 provides for withholding tax “at the rate of 0% or any other rate as specified in a decision issued by the Cabinet”. The Cabinet has set that rate at zero for all categories.
| Payment to a non-resident | UAE withholding tax |
|---|---|
| Dividends to foreign shareholders | 0% — pay the full amount |
| Interest to non-resident lenders | 0% |
| Royalties and licence fees | 0% |
| Service and management fees | 0% |
| Branch profits repatriated to head office | 0% |
This applies whether the payer is a mainland LLC, a free zone company, or a DIFC or ADGM entity. A Dubai company paying a management fee to its UK parent remits the full amount, with no deduction and nothing to report to the Federal Tax Authority.
In much of the world that same payment would suffer a deduction of 10% to 25% at source. This is one of the more commercially significant features of the UAE regime, and it is easy to take for granted.
Do I need to register or file a withholding tax return?
Registration and filing
No. While the rate remains at 0%, there is no requirement to register as a withholding agent, deduct any amount, or file a withholding tax return.
You will sometimes see commentary suggesting that withholding tax returns are “coming” to the UAE. That is speculation. No filing mechanism has been published, because at a zero rate there is nothing to file.
What is true is that the obligation to remit exists in the law and is dormant. Article 45(2) states that withholding tax payable “shall be deducted from the gross amount of the payment and remitted to the Authority in the form and manner and within the timeline prescribed by the Authority”. That machinery sits ready. It simply has nothing to collect at present.
Could the rate change?
Legally, yes — and the route is short. Because Article 45 delegates the rate to a Cabinet Decision, a positive rate could be introduced without amending the Corporate Tax Law itself. No parliamentary process, no new decree-law.
As matters stand in 2026 the rate remains at 0%, and there has been no indication of a change. The framework is best read as future-proofing rather than a signal of anything imminent.
What this means practically
If you are structuring long-term cross-border payment flows, do not assume the 0% rate is permanent simply because it is written into the law. It is not written into the law — the law provides for a rate to be set, and the current setting is zero. Groups with material outbound payments should know what a positive rate would cost them.
The question that actually matters: foreign tax on money coming in
Here is where most UAE businesses have a real and often unnoticed problem.
The UAE charging 0% does nothing to stop other countries withholding tax on payments made to you. If you invoice a customer in India, Pakistan, Egypt or the Philippines, that customer’s own tax authority may require them to deduct tax before the money reaches your account.
The result is familiar: an invoice for AED 300,000 is settled with AED 240,000, and nobody in the business can explain where the rest went.
The UAE’s 0% rate is about money going out. Foreign withholding tax is about money coming in — and that is where the cost usually is.
How treaty relief works ?
The UAE maintains an extensive network of double tax agreements. Those treaties typically reduce the withholding rate a foreign country may apply — sometimes to zero, often to 5% or 10% rather than a domestic rate of 20% or more.
The relief is not automatic. Treaty rates apply only when properly claimed, and the claim generally has to be made before or at the time of payment, with documentation the foreign payer can rely on. Once the money has been deducted and remitted, recovering it means a refund claim in the foreign jurisdiction, which is slow and sometimes not worth pursuing.
What a Tax Residency Certificate does ?
A UAE Tax Residency Certificate is the document that proves to a foreign tax authority that you are resident in the UAE and therefore entitled to the relevant treaty. It is usually the prerequisite for accessing a reduced rate, and for supporting a foreign tax credit claim afterwards.
- Identify the treaty between the UAE and your customer’s country, and the rate it permits for your type of income.
- Obtain a Tax Residency Certificate from the Federal Tax Authority for the relevant period.
- Provide it to the payer before invoicing, along with whatever form their tax authority requires.
- Keep the withholding certificates the payer issues, since these support any credit claim in your UAE return.
Withholding Tax Credit and Foreign Tax Credit are not the same thing
These two provisions are frequently confused, and the distinction is straightforward once separated.
| Withholding Tax Credit | Foreign Tax Credit | |
|---|---|---|
| Provision | Article 46 | Article 47 |
| What it relieves | UAE withholding tax suffered | Foreign tax paid abroad |
| Relevant today | No — the UAE rate is 0%, so none is suffered | Yes |
| Typical use | Dormant | Crediting foreign withholding against UAE Corporate Tax |
In short: Article 46 would matter only if the UAE itself began withholding. Article 47 is the one businesses use now, to credit tax already paid abroad against UAE Corporate Tax payable in the same period.
One important interaction: if you have elected the Foreign Permanent Establishment exemption, a Foreign Tax Credit is not available on that income. The income is excluded from the UAE tax base entirely, so there is no UAE liability for the credit to reduce.
Who should pay attention to this ?
- UAE businesses invoicing overseas customers — particularly in South Asia, Africa and parts of the Middle East, where domestic withholding rates are high and treaty claims must be made in advance.
- Holding companies receiving foreign dividends — treaty access can be the difference between receiving 80% and 100% of a distribution.
- Groups with material outbound payments — worth knowing your exposure if the 0% rate were ever set higher.
- Non-residents earning UAE-sourced income — Article 45 is the provision that would apply to you, and the PE and nexus questions matter regardless of the rate.
What to do now ?
- Review your last twelve months of foreign receipts. Compare what you invoiced against what actually arrived. Any shortfall is likely foreign withholding tax.
- Check whether a treaty covered it. If one did and you did not claim, you paid tax you did not owe.
- Obtain a Tax Residency Certificate if you invoice overseas and do not hold one.
- Put the certificate into your onboarding process for new foreign customers, so the claim is made before the first invoice rather than after the first deduction.
- Collect withholding certificates from foreign payers and keep them with your tax records for the Foreign Tax Credit claim.
- Do not build a structure on the assumption that 0% is permanent. It is a Cabinet setting, not a statutory guarantee.
How Fintra Global can help ?
Most of the value in this area is not in the UAE position — it is in recovering or preventing foreign withholding tax on your inbound payments.
We review your foreign receipts to identify where tax has been deducted, confirm which treaty applies and at what rate, obtain Tax Residency Certificates from the Federal Tax Authority, and prepare the documentation your foreign customers need so that the reduced rate is applied at source rather than reclaimed later. Where tax has already been withheld, we assess whether a Foreign Tax Credit is available in your UAE Corporate Tax return.
Invoicing overseas customers and unsure whether you are losing tax at source? fintraglobal.com · +971 55 467 2256
This article is general guidance current as at October 2026 and is not tax advice. Withholding tax rates and categories are set by Cabinet Decision and may change. Treaty positions depend on the specific agreement and your circumstances.