The UAE is introducing E-Invoicing to modernize business compliance and VAT reporting. This guide explains what it means, the key implementation dates, and how your business can prepare before the deadline.
This guide has been updated to reflect the detailed legislation — the Ministry of Finance Guidelines V2.0 (26 October 2026), Ministerial Decisions No. 243 and 244 of 2025 and their amendments, including Ministerial Decision No. 197 of 2026, Ministerial Decision No. 168 of 2026 on provider accreditation, and Cabinet Decision No. 173 of 2026 on penalties — and the current phased timeline.
Updated 28 October 2026
Two changes matter most. First, E-Invoicing applies to any business operating in the UAE, whether or not it is VAT registered — not only to VAT-registered businesses. Second, each phase has two dates: a deadline to appoint an Accredited Service Provider, and a later go-live date. The appointment date is the one that binds. This version also reflects the October 2026 changes: a two-year exclusion for transactions inside a VAT group, records no longer having to be stored in the UAE, the end of the system-failure notice, new accreditation rules for providers, and the Ministry’s Guidelines V2.0.
What is UAE E-Invoicing?
E-Invoicing is the process of creating, sending, receiving, and storing invoices in a structured electronic format rather than using paper documents or simple PDF files.
Unlike emailing a PDF invoice, E-Invoicing enables invoice data to be exchanged automatically between businesses through accredited service providers. This allows tax authorities to receive standardized transaction data while improving accuracy, reducing manual work, and enhancing business efficiency.
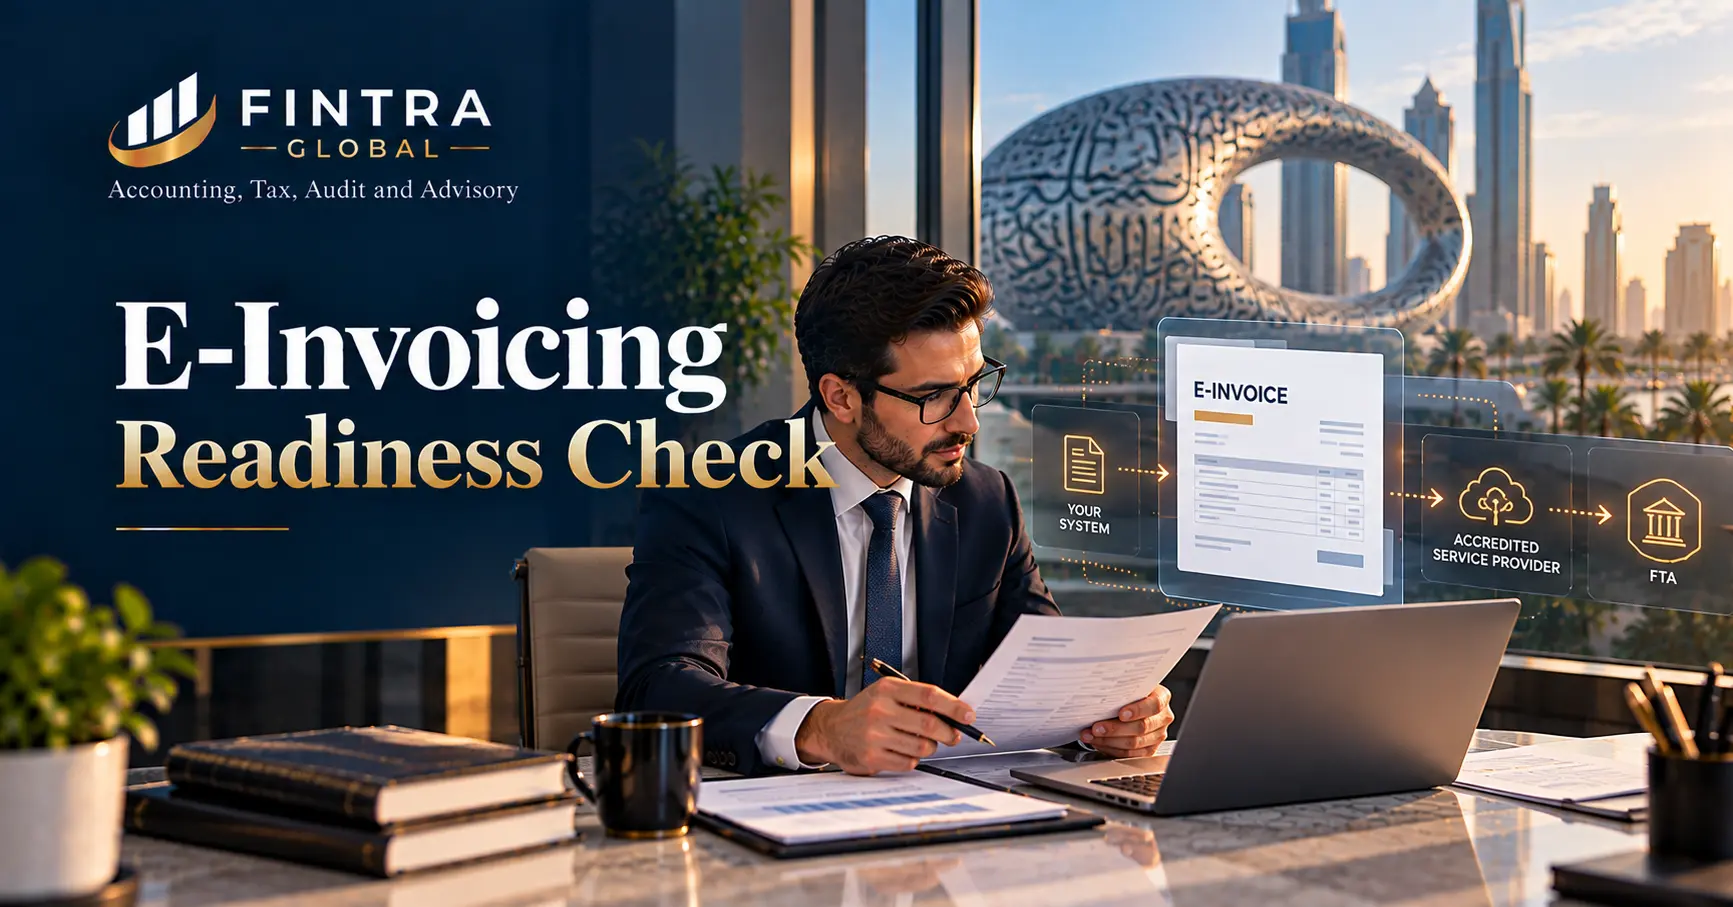
In technical terms, a UAE e-invoice is a structured XML file in the Peppol PINT AE format. It travels through a five-corner model: your system passes the invoice to your accredited provider, who validates it, transmits it to your customer’s provider, and reports the data to the Federal Tax Authority in near real time. Unlike Saudi Arabia’s system, there is no QR code requirement.
The new system is designed to create a faster, more transparent, and more reliable invoicing ecosystem across the UAE.
| PDF invoice by email | UAE e-invoice | |
|---|---|---|
| Format | PDF or Word document | Structured XML (Peppol PINT AE) |
| How it travels | Email attachment | Accredited provider network |
| Read by | A person | Software, automatically |
| Tax authority | Sees it only on audit | Receives the data in near real time |
| Counts as compliant | No | Yes |
Why is the UAE introducing E-Invoicing?
The UAE government aims to modernize its tax infrastructure and strengthen VAT compliance through digital reporting.
The objectives include:
- Reducing invoice fraud
- Improving VAT compliance
- Minimising manual data entry
- Increasing invoice processing efficiency
- Enhancing financial transparency
- Supporting the UAE’s wider digital economy initiatives
Many countries have already adopted similar systems, and the UAE is following international best practices to simplify tax administration while reducing compliance risks.
Who will be affected?
This is the point most often misunderstood, and the legislation is explicit about it.
E-Invoicing applies to any person conducting business in the UAE, for every business transaction — regardless of VAT registration status.
Earlier commentary, including the original version of this article, described the framework as applying to VAT-registered businesses. That is not correct. If you run a business in the UAE and issue invoices to other businesses, you are in scope even if your turnover has never reached the VAT registration threshold.
Free zone entities are included, with no carve-out for a 0% corporate tax position. Businesses with no Tax Registration Number will need to register with the Federal Tax Authority simply to obtain the identifier the system runs on. For most companies, Corporate Tax registration is the route that issues it.
Newly established businesses get no settling-in period. Guidelines V2.0 state that a business newly established and within scope must appoint an Accredited Service Provider and complete onboarding before it issues its first invoice, whatever its date of establishment.
| In scope | Outside the system |
|---|---|
| Business-to-business transactions | Sales to private consumers (B2C) |
| Business-to-government transactions | Certain exempt financial services |
| Free zone entities | International passenger transport |
| Businesses not registered for VAT | Government sovereign activities not competing with the private sector |
| Newly established businesses, from their first invoice | Transactions between members of the same VAT group (until 31 December 2028) |
Exclusions are narrow and specific. If you are unsure whether a particular transaction type falls outside the system, treat it as in scope until confirmed.
Guidelines V2.0 add one clarification for healthcare: where a hospital treats a patient and an insurer settles the claim, the patient remains the recipient, so the insurer’s payment is not a B2B transaction for e-invoicing.
UAE E-Invoicing Implementation Timeline
The Ministry of Finance has announced a phased rollout. Each phase now carries two dates: the deadline by which you must have appointed an Accredited Service Provider, and the date from which you must actually be issuing e-invoices.
| Phase | Appoint a provider by | Go live from |
|---|---|---|
| Voluntary pilot | — | 1 July 2026 |
| Revenue above AED 50 million | 30 October 2026 | 1 January 2027 |
| Revenue below AED 50 million | 31 March 2027 | 1 July 2027 |
| Government entities | 31 March 2027 | 1 October 2027 |
The date that binds
The appointment deadline is the real deadline. You cannot go live without a provider already onboarded, and onboarding is an integration project rather than a purchase. Every business in the same wave will be approaching the same small pool of accredited providers in the same quarter.
The first of these dates moved. In May 2026 the Ministry amended Ministerial Decision No. 244 of 2025 to push the AED 50 million appointment deadline from 31 July to 30 October 2026, following feedback on provider availability and pricing. The go-live date for that group did not move. The same announcement relaxed the accreditation rules for providers, permitting white-label and outsourced models while leaving compliance responsibility with the accredited provider.
The October 2026 amendments did not move any date. If your revenue is AED 50 million or more and you have not yet appointed a provider, this is now urgent: go-live is 1 January 2027. Separately, Ministerial Decision No. 168 of 2026 replaced the accreditation rules from 1 October 2026 and removed the pre-approval stage, so check any provider against the Ministry’s current accredited list.
Revenue is measured as gross income for your most recent accounting period. Businesses should regularly review official updates, as implementation details may continue to evolve.
What is an Accredited Service Provider, and do I need one?
Yes. Appointing an Accredited Service Provider is mandatory for every business in scope, whatever accounting software you use.
This is the question we are asked most often, usually by businesses running Zoho, Tally, QuickBooks or Xero. Your accounting software produces the invoice data. Only an accredited provider can convert that data into the required XML format, transmit it across the Peppol network, and report it to the Federal Tax Authority.
- One provider covers both your sales invoices and your purchase invoices.
- You initiate onboarding from your own EmaraTax account, not from the provider.
- Providers must hold Peppol certification and appear on the Ministry’s accredited list. Since 1 October 2026 there is no “pre-approved” status: a provider is either accredited or it is not.
- You remain responsible for the accuracy of the data you send, even though the provider transmits it.
What actually delays businesses
In readiness work, the obstacle is rarely the technology. It is master data. Missing buyer Tax Registration Numbers, incomplete addresses, and no field to store a counterparty’s participant identifier all cause invoices to fail validation and bounce back.
Each bounced invoice is a document not transmitted on time. Cleaning customer records is slow, unglamorous work, and it is far cheaper to do it months ahead than under deadline pressure.
How quickly an e-invoice must go out
Ministerial Decision No. 197 of 2026 restates the general rule: an electronic invoice or electronic credit note must be issued and transmitted through the system within 14 business days of the date of the business transaction.
If you are VAT registered, the VAT law’s tax invoice deadlines still apply, and they generally require a tax invoice within 14 calendar days of the date of supply. VAT-registered businesses should keep working to the VAT deadline. The business-day window mainly matters for businesses that are not registered for VAT.
Penalties for non-compliance
Cabinet Decision No. 173 of 2026 now governs e-invoicing penalties, replacing Cabinet Decision No. 106 of 2025. Its full text had not been published when this guide was updated, so the amounts below are those set by Decision 106. These amounts sit on top of ordinary VAT and tax procedure penalties, not instead of them.
| Failure | Penalty |
|---|---|
| Operating without an appointed provider | AED 5,000 per month — a partial month counts as a full month |
| Invoice not transmitted in time | AED 100 per invoice, capped at AED 5,000 per month |
| Credit note not transmitted in time | AED 100 per credit note, capped at AED 5,000 per month (a separate cap) |
| Change in registered data not notified to your provider | AED 1,000 per day, with no cap |
The uncapped daily penalty is the one to watch: it applies when you do not tell your provider about a change in your registered data, such as a new address or licence details. The separate duty to notify the Authority of a system failure within two business days was repealed by Ministerial Decision No. 197 of 2026 from 1 October 2026.
Keeping e-invoice records
Electronic invoices, electronic credit notes and their associated data must be kept for the period set by the Tax Procedures Law: five years after the relevant tax period for a Taxable Person, and seven years for real estate records.
Ministerial Decision No. 197 of 2026 removed the requirement to store this data inside the UAE. What matters now is that the records sit in an electronic system that preserves their integrity, and that they can be retrieved and produced to the FTA in complete, readable form whenever it asks. Guidelines V2.0 confirm that “associated data” means the data needed to support the integrity and auditability of the e-invoice itself, not your general business documents.
Benefits of E-Invoicing
Businesses that prepare early can benefit from:
- Faster invoice processing
- Reduced manual errors
- Improved VAT compliance
- Better cash flow visibility
- Lower administrative costs
- Enhanced financial reporting
- Easier audit readiness
- Stronger data security
Over time, E-Invoicing is expected to improve operational efficiency while reducing paperwork and repetitive administrative tasks.
How should businesses prepare?
Preparation should begin well before mandatory implementation. Consider taking the following steps:
- Confirm which phase you are in. Check your gross income for the most recent accounting period against the AED 50 million threshold.
- Audit your customer and supplier data. Every business counterparty needs a valid Tax Registration Number and a complete address. This usually takes longer than expected.
- Review your existing invoicing process and identify anything still handled manually or outside your accounting system.
- Check what your accounting software can export and whether your provider of choice integrates with it. Note that software alone is not sufficient — an accredited provider is still required.
- Shortlist accredited providers early, using the Ministry’s current list. Compare integration support and pricing before the queue forms in your phase.
- Register with the Federal Tax Authority if you do not yet hold a Tax Registration Number. For most companies this is done through Corporate Tax registration.
- Map any transactions inside a VAT group. They are excluded until 31 December 2028, and then come into scope in full.
- Consult your accountant or tax advisor regarding readiness and the gap between where you are and what go-live requires.
- Stay updated with announcements from the Ministry of Finance and the Federal Tax Authority.
Early preparation will reduce disruption once compliance becomes mandatory.
Final Thoughts
E-Invoicing represents one of the biggest changes to business compliance in the UAE in recent years. While the rollout is phased, businesses that prepare now will find the transition far easier than those waiting until the final implementation dates.
Understanding the requirements, reviewing internal processes, and working with experienced tax professionals can help ensure your business remains compliant while benefiting from a more efficient invoicing system.
How Fintra Global can help
We work with UAE businesses at both ends of this.
If you want to handle it in-house, our e-invoicing readiness review confirms which phase applies to you, audits your customer and supplier data against what the format requires, reviews what your accounting system can produce, and gives you a written plan with dates.
If you would rather not deal with it at all, our accounting and e-invoicing package covers your bookkeeping, raises compliant invoices on your behalf, and submits them to the Federal Tax Authority through an accredited provider on an ongoing basis. Pricing is based on invoice volume.
Speak to us about your e-invoicing readiness: fintraglobal.com · +971 55 467 2256